

Beyond repair: what makes a dwelling?
Share this article

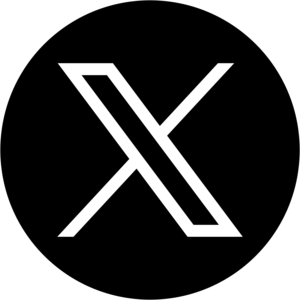

Severely dilapidated properties can remain dwellings for tax purposes, but recent cases demonstrate when their condition may cross the residential threshold.
Key Points
What is the issue?
Two recent tribunal decisions consider when a severely dilapidated property ceases to be suitable for use as a dwelling, demonstrating the importance of the property’s characteristics and the extent of work required.
What does it mean to me?
A property does not cease to be residential simply because it is uninhabitable. Advisers must consider its history, structural condition, hazards and whether the cumulative defects have fundamentally altered its residential character.
What can I take away?
The threshold for losing residential status is high but can be crossed. Contemporaneous evidence of the property’s condition, structural defects, hazards and the extent of remedial works may prove crucial.
Two recent tribunal decisions involving severely dilapidated properties demonstrate just how difficult it can be to establish when a building has ceased to be suitable for use as a dwelling. They also provide some useful lessons for advisers dealing with properties in a poor state of repair.
In the case of LMT Property Investors Ltd v Revenue Scotland [2026] FTSTC 3, the First-tier Tribunal for Scotland (Tax Chamber) ruled that a highly dilapidated property was still legally a ‘dwelling’, meaning that the company was liable to pay the additional dwelling supplement.
The cases have particular relevance to farmers and landowners, who may own residential properties that have stood empty for long periods and fallen into serious disrepair. Unlike property investors deliberately acquiring ‘fixer-uppers’, they may find themselves dealing with old houses on a farming estate that have simply deteriorated over time.
There may also be wider tax implications. Ironically, a property that remains a dwelling for stamp tax purposes may potentially fail to qualify for agricultural property relief or business property relief if it is neither occupied for agricultural purposes nor used as part of the farming business. The interaction with inheritance tax therefore needs to be considered separately: see HMRC v AM Brander (as Executor of the will of the late fourth Earl of Balfour) [2010] UKUT 300 (TCC).
The case was also notable for another reason. The director of LMT Property Investors Ltd had used artificial intelligence to help prepare his arguments, resulting in inaccurate references to case law, including a non-existent case, being presented to the tribunal.
A property in need of renovation
LMT Property Investors Ltd bought a property at auction with the intention of renovating and selling it. It had been empty for approximately 12 years and the company knew that substantial renovation would be required.
The director obtained a home report but carried out no other research and did not view the property before buying it. At the time of purchase, the property had serious defects. These included a sagging ceiling caused by a faulty skylight, severe damp, dangerous electrical wiring requiring complete replacement, lead-contaminated mains drinking water, and missing or damaged windows, doors and roofing.
The company initially submitted its land and buildings transaction tax return on the basis that the property was residential. It subsequently amended the return, arguing that the property was non-residential because it was not suitable for use as a dwelling, and sought repayment of the additional dwelling supplement.
Revenue Scotland accepted that the property was unlikely to have been capable of occupation at the effective date of the transaction. However, it did not consider this to be determinative. Although work would be needed to make the property habitable, Revenue Scotland considered that it retained the characteristics of a dwelling.
The company appealed.
What makes a dwelling?
At the heart of LMT Property Investors Ltd’s argument was the condition of the property at the effective date. Considered objectively, the company argued, it was neither habitable nor safe and therefore could not be suitable for use as a dwelling.
The tribunal concluded that this was not the correct test.
The Court of Appeal’s decision in Mudan v HMRC [2025] EWCA Civ 799 had made it clear that there should not simply be a ‘snapshot’ of the property at the effective date. Instead, the test requires consideration of the fundamental characteristics and nature of the building over a period of time.
Mudan is a landmark UK Court of Appeal ruling. It established that a property which has previously been used as a dwelling can remain residential for stamp duty land tax purposes even if it is severely dilapidated or vandalised when purchased. The property does not have to be ‘move-in ready’ on the date of completion.
The important distinction is between a building that retains the fundamental characteristics of a dwelling and requires repairs or renovation, and one where those characteristics have been lost.
In LMT Property Investors Ltd, the First-tier Tribunal found that the level of dilapidation had not removed the property’s ‘essential character’ as a dwelling. The remedial works required were substantial, but none were considered so hazardous as to make the restoration unviable.
The property had also been used as residential accommodation for many years, although it was unoccupied at the time of purchase following the owner’s death, and was still fully furnished when the company bought it. Its subsequent major refurbishment was undertaken at the company’s choice and did not alter the property’s character at the time of acquisition. It remained, in the tribunal’s view, a ‘fixer-upper’ that was suitable for use as a dwelling. The appeal was therefore dismissed.
When the line is crossed
A subsequent decision demonstrates, however, that there is a point at which the condition of a former home can take it outside the residential property rules. In Oakwood Great Oak Ltd v HMRC [2026] UKFTT 1138 (TC), the First-tier Tribunal reached the opposite conclusion when applying the principles established in Mudan.
The question was whether the property was ‘residential property’ within Finance Act 2003 s 116(1)(a) at the effective date of the transaction and, in particular, whether it remained ‘suitable for use as a dwelling’ for the purposes of stamp duty land tax.
The tribunal considered its previous residential use and recognisable residential layout alongside its structural defects, extensive deterioration and widespread asbestos contamination. It was not sufficient to consider any one of those factors in isolation. The tribunal emphasised the importance of looking at their cumulative effect.
The judge concluded: ‘This was not merely a dwelling awaiting renovation. Nor was it simply an unmodernised property requiring substantial refurbishment.’ The exceptional scale and intrusive nature of the work required had fundamentally altered the character and identity of the property so that it no longer possessed the characteristics of a dwelling. The taxpayer’s appeal was therefore allowed.
Comparing the two cases
The different outcomes in LMT Property Investors Ltd and Oakwood Great Oak Ltd demonstrate the importance of degree. Both properties had previously been dwellings and both required substantial work. But in LMT Property Investors Ltd, the defects amounted to severe dilapidation that could nevertheless be addressed through standard and viable remedial works. The property retained its essential residential character.
In Oakwood Great Oak Ltd, however, the combination of structural deterioration and serious hazards had gone considerably further. An accumulation of catastrophic structural failures required the dismantling and stripping of the property. Looking at the evidence cumulatively, the tribunal found that the property had ‘crossed the line’ identified in Mudan and was no longer suitable for use as a dwelling.
The distinction is therefore not simply between a habitable and an uninhabitable property. The severity of the defects, the viability of repair and the nature and extent of the work required all matter. Nor does the fact that it is theoretically possible to repair a building necessarily determine its status.
The two decisions therefore provide useful markers on either side of what remains a highly fact-sensitive boundary. Standard achievable renovation, even where extensive, will not necessarily be sufficient to take a property outside the residential rules. However, Oakwood Great Oak Ltd demonstrates that the threshold, although high, can be crossed where the scale and nature of the works required are so extensive that the property has lost its essential character as a dwelling.
The AI warning
There was a separate lesson for advisers in LMT Property Investors Ltd.
The company’s director, who was unrepresented, had used AI to help prepare his case. This resulted in inaccurate references to case law and the citation of a non-existent case, as well as a number of incorrect substantive legal arguments.
The tribunal accepted that the director had acted entirely in good faith and had not attempted to mislead it. His conduct was therefore not treated as contempt of court. Nevertheless, the judge pointed out that AI could be ‘unreliable’ and produce ‘hallucinations’.
The episode provides a useful reminder that AI-generated legal and tax research must be checked against authoritative sources. AI can assist with research and preparation, but apparently convincing citations or propositions should not be relied upon without verification.
Lessons for property owners and advisers
The decisions are particularly relevant where farms and landed estates contain houses that have stood empty or deteriorated over many years. Establishing the condition of the property at the relevant time will be crucial; the fact that it cannot immediately be occupied will not, by itself, determine its status.
Advisers should therefore consider the property’s history and characteristics, the severity of any structural defects or hazards, and the scale and nature of the works required. Contemporaneous surveys, photographs and other evidence of its condition may be particularly important in demonstrating whether a former dwelling has crossed the line into non-residential property.
Ultimately, the question is not simply whether someone could move into the property on completion, but whether, considered objectively and in the round, the building still possesses the fundamental characteristics of a dwelling.
© Getty images